Best for agency-managed India bookings: PayLite through Mann Travel AU. Best for comparing an existing borrowing facility: your card issuer’s instalment option, if offered. Best for avoiding a new repayment commitment: payment in full. This 2026 guide compares fly now pay later flights by booking practicality, repayment obligations and what happens when your plans change—not by an advertised instalment amount.
In-short:
- Mann Travel AU offers fly now pay later flights through PayLite for travellers booking Australia-to-India journeys.
- Compare the full repayment obligation, payment dates and cancellation terms before choosing a flight payment plan.
- Existing-card instalments and personal loans are alternatives to investigate, not confirmed agency payment products.
- Payment in full is the comparison baseline when you want to avoid a new borrowing commitment.
Why this matters
An India trip involves two separate decisions: which flight suits your journey, and how you will pay for it. A convenient payment schedule does not make an inconvenient connection worthwhile. Equally, a suitable itinerary does not make unclear borrowing terms acceptable.
For your 2026 booking, compare the flight and finance separately before accepting either. Start with the arrival date you need in Delhi, Mumbai, Amritsar or your final destination, then check whether the repayment schedule fits your household budget.
Mann Travel AU is best suited to travellers who want to discuss fly now pay later flights alongside an agency-managed Australia-to-India booking. That is a booking-service recommendation, not a claim that PayLite has the lowest borrowing cost.
What makes the best fly now pay later flights?
Use these criteria before comparing payment approaches:
- Booking certainty: Establish when your reservation becomes a ticket and what confirmation you receive.
- Total obligation: Compare everything you must repay, including applicable borrowing charges, rather than the headline instalment.
- Payment timing: Check the first payment, subsequent due dates and whether payments continue after departure.
- Change handling: Understand the separate processes for changing the flight and adjusting any associated finance.
- Practical support: Know who handles the airline booking and who handles repayment questions.
- Budget fit: Choose a commitment you can meet without depending on an uncertain refund or future income.
These criteria apply to every option below. The ranking reflects different booking needs; it is not a verified comparison of competing lenders’ terms.
Flight payment options at a glance
Only PayLite is identified in the supplied brand information as an agency payment offering. The other entries are payment approaches to investigate independently, and payment in full is included as a non-financed benchmark.
| Payment approach | Best for | Standout feature | Key limitation |
|---|---|---|---|
| PayLite through the agency | Coordinating an India flight booking and payment-plan enquiry | Discuss the itinerary and payment arrangement through the booking agency | You still need the actual finance terms before deciding |
| Existing-card instalments, if offered | Comparing a facility attached to a card you already hold | Keeps the comparison focused on an existing account | The issuer must confirm eligibility and applicable terms |
| A separately arranged personal loan | Assessing a borrowing decision independently of the flight seller | Separates finance selection from itinerary selection | Adds a separate application and lender relationship |
| Payment in full | Avoiding a new flight-related repayment commitment | Removes the need to choose a new borrowing arrangement | Requires the booking amount from existing funds |
1. PayLite: best for agency-managed India flight bookings
Mann Travel AU offers Book Now Pay Later through PayLite alongside its international flight booking service. For an Australia-to-India trip, that gives you a named payment option to ask about while discussing your itinerary.
The useful distinction is coordination. You can raise the flight and payment questions together, but you must still establish which organisation is responsible for each part of the arrangement.
PayLite pros:
- It is a payment option explicitly identified by the booking agency.
- You can discuss it in the context of your actual India itinerary.
- It gives you a specific arrangement to compare against paying in full.
PayLite cons:
- The product name alone does not establish your repayment obligations.
- Airline changes and finance adjustments require separate clarification.
- A manageable instalment does not prove that the full commitment suits your budget.
For a 2026 journey, ask for the current agreement before accepting the booking arrangement. Check who provides the finance, when payments begin and what happens if the airline changes your itinerary.
Best for: Travellers who want agency help arranging an India flight and discussing a payment plan in the same booking conversation.
Verdict: Hold until you have reviewed the repayment agreement and ticketing conditions. PayLite belongs first on this shortlist because it is the confirmed agency offering, not because its financial terms have been ranked against other providers.
2. Existing-card instalments: best for checking an existing facility
If your card issuer offers instalments for an eligible travel purchase, compare that arrangement with the agency’s payment option. Treat the issuer’s current terms as the source of truth; do not assume every card or transaction qualifies.
This approach starts with an account you already hold. It does not remove the need to examine the borrowing commitment or establish whether the agency accepts the intended payment method.
Existing-card instalment pros:
- You can compare an existing account before considering a separate lender.
- The issuer can explain how the proposed arrangement interacts with your account.
- You can assess the payment schedule independently of the flight itinerary.
Existing-card instalment cons:
- Eligibility and transaction treatment require issuer confirmation.
- An airline refund and a card repayment adjustment are separate matters to check.
- Existing borrowing remains relevant when deciding whether another commitment fits.
Ask whether the transaction must occur before an instalment arrangement can be requested. That distinction matters: you should understand the sequence before making a flight purchase you intend to finance.
Best for: Travellers who already hold a card and want to check an issuer-provided option before opening another borrowing arrangement.
Verdict: Hold until your issuer confirms the exact transaction treatment and repayment terms. Do not book on the assumption that you can convert the purchase later.
3. Personal loan: best for separating finance from flight selection
A personal loan is a separate borrowing product rather than a flight-specific payment plan. If you are considering one, assess the loan on its own terms before using it to fund travel.
Separating the decisions gives you a clear comparison task: first assess whether the borrowing is appropriate, then compare the itinerary. It also creates another organisation to deal with if your circumstances change.
Personal loan pros:
- You can assess finance independently of the travel seller.
- A lender’s written offer gives you a defined agreement to review.
- You can distinguish the borrowing decision from the airline’s fare conditions.
Personal loan cons:
- It adds a separate application and repayment relationship.
- Cancelling a flight does not establish what happens to the loan.
- Travel urgency can distract from reviewing the borrowing terms carefully.
For a 2026 trip, do not build the application around an unconfirmed flight quote. Establish how long the quote applies, when funds would be needed and what happens if the itinerary changes before booking.
Best for: Travellers already assessing a separate loan who want to keep lender selection distinct from choosing flights.
Verdict: Hold until you have assessed the loan independently of the travel deadline. A pressing departure date is not a reason to skip reviewing a borrowing agreement.
4. Payment in full: best for avoiding a new repayment commitment
Payment in full is not a fly now pay later plan. It belongs in this comparison because it provides the clearest baseline for deciding whether you need finance at all.
If you can pay from existing funds without compromising essential spending, compare that choice against the obligations of a payment plan. Paying upfront does not remove airline change or cancellation conditions.
Payment-in-full pros:
- It avoids taking on a new flight-related borrowing agreement.
- There is no new instalment schedule to manage after departure.
- It lets you focus the booking comparison on the itinerary and fare rules.
Payment-in-full cons:
- It requires the booking amount from existing funds.
- It reduces the cash you retain for other needs.
- Airline refund conditions still require careful review.
Keep a clear distinction between having enough money to complete the transaction and having enough money for the whole journey. Include accommodation, onward transport and essential household commitments in your planning.
Best for: Travellers with sufficient existing funds who want to avoid a new repayment obligation.
Verdict: Buy outright only when the payment leaves essential spending covered. Otherwise, reassess the trip and payment choices rather than treating finance as automatic.
Check the booking before choosing the plan
Use 3 payment checkpoints for your 2026 comparison: before ticketing, before departure and after cancellation. At each checkpoint, establish what you owe and which organisation handles the next action.
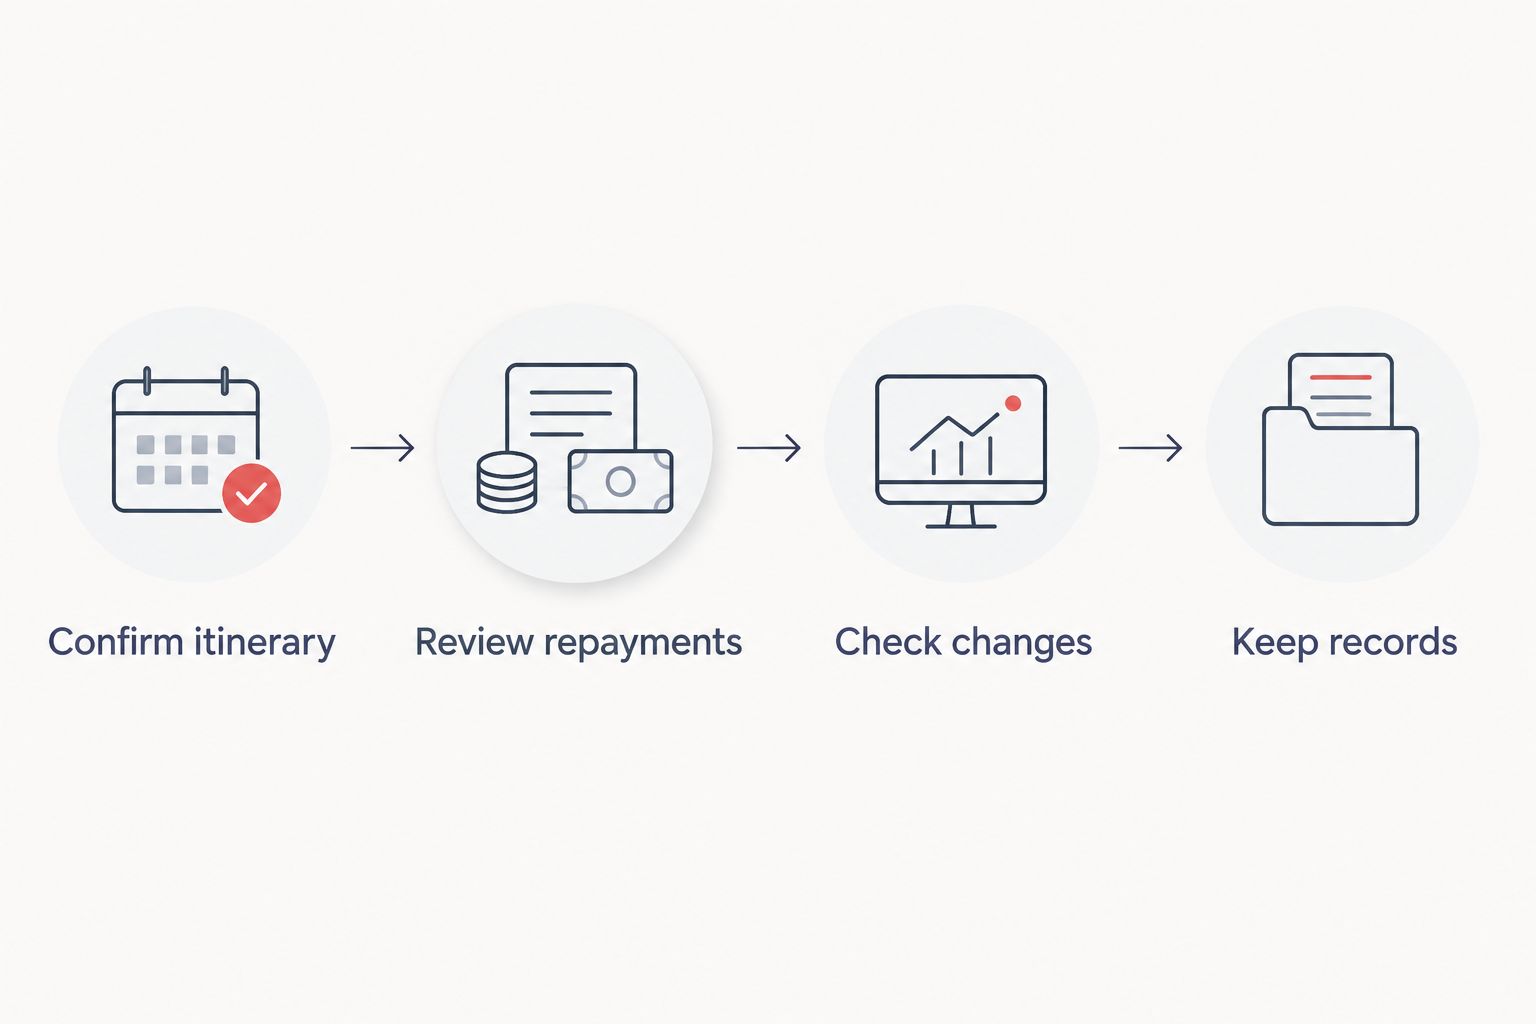
The practical sequence is straightforward:
- Confirm itinerary: Check departure and arrival dates, connecting airports and the final destination.
- Review repayments: Read the payment schedule and full borrowing agreement.
- Check changes: Read the airline conditions and ask how changes affect the finance arrangement.
- Keep records: Save the booking confirmation and payment agreement separately.
Keep 2 separate records: the flight documentation and the finance documentation. A booking reference does not explain your repayment obligations, and a payment agreement does not replace your flight confirmation.
Check 4 itinerary details before authorising payment: passenger names, travel dates, connecting airports and the final destination. Read the arrival date carefully when the journey crosses midnight; your departure date is not necessarily your arrival date.
Discuss your India flight booking
Ask about your Australia-to-India itinerary and the PayLite payment option before committing.
How the payment approaches were ranked
PayLite ranks first for agency coordination because it is the named payment option offered by Mann Travel AU. Existing-card instalments and personal loans are included as separate approaches to investigate, not as endorsed or confirmed agency products.
Payment in full remains the baseline for avoiding new borrowing. No option receives a lowest-cost ranking: that comparison requires the actual agreements for your circumstances.
For 2026, the deciding criteria are booking certainty, total obligation, payment timing, change handling, support responsibility and budget fit. Use the same criteria for every written offer so a smaller instalment does not distract from a longer commitment.
Which flight payment option should you choose?
Start with the itinerary, then choose the payment arrangement. If you want agency-managed fly now pay later flights, ask Mann Travel AU about PayLite and request the terms before committing.
If you already have an issuer-provided instalment option, compare its written conditions independently. If you can comfortably pay from existing funds, use payment in full as the benchmark rather than assuming a payment plan is necessary.
Your final choice should answer a practical question: can you meet the commitment even if the trip changes? If that answer depends on receiving a refund by a particular date, resolve the uncertainty before booking.
FAQ
What’s the best fly now pay later option for an India trip?
PayLite is the named option to discuss with Mann Travel AU when you want agency-managed Australia-to-India flight booking. Choose it only after reviewing the actual repayment agreement and ticketing conditions; it is not established here as the lowest-cost finance option.
Can I book Australia-to-India flights with PayLite?
Mann Travel AU identifies Book Now Pay Later through PayLite among its services. Ask how it applies to your proposed itinerary and review the current agreement before committing.
Is a flight payment plan better than using my credit card?
Neither is automatically better. Compare the written repayment obligations, payment dates and change handling for the specific options available to you, and ask your issuer whether the intended transaction qualifies.
Does cancelling my flight cancel the repayments?
Do not assume that cancelling a flight cancels its associated finance agreement. Ask the travel agency and finance provider separately how the cancellation, any refund and remaining repayments are handled.
Can I choose a payment plan for a last-minute India trip?
Ask the agency whether the proposed payment arrangement can meet the booking’s ticketing deadline. Do not treat an enquiry or application as confirmation that the flight has been ticketed.
What should I check before accepting a flight payment plan?
Check the full repayment obligation, due dates, ticketing conditions and cancellation process. Keep the flight confirmation and finance agreement as separate records so you can identify who handles each issue.
Should I pay in full instead of choosing instalments?
Payment in full avoids a new borrowing commitment when you use existing funds. Choose it only if the payment leaves essential spending covered, and still check the airline’s change and refund conditions.
One last thing
The payment schedule does not tell you whether the flight is suitable. Before accepting a 2026 booking, read the itinerary aloud from departure airport to final arrival, including every connection and date change.
Then read the repayment dates separately. If either document is unclear, settle that question before authorising the booking—not at the airport or after the first payment falls due.
Related guides
- Best airlines for Melbourne to Amritsar flights
- Best airlines for families flying to India
- Best airlines for Sydney to Delhi flights
- Best airlines for Melbourne to Mumbai flights

